New Data Show How ICE and CBP Are Using Their Reconciliation Funding
The One Big Beautiful Bill Act (OBBBA) and the Secure America Act (SAA) have transformed the budgets of Immigration and Customs Enforcement (ICE) and Customs and Border Protection (CBP). Federal spending data through August show that ICE has obligated $19.8 billion of the laws’ funding, while CBP has obligated $40.4 billion. $144.0 billion of the laws’ original appropriations remain available, four and a half times the agencies’ combined annual funding.
At their average monthly pace from June through August, CBP would obligate its remaining OBBBA funding in about 12 months and its remaining SAA funding in about 34 months. ICE would need 29 months to obligate its remaining SAA funding and 73 months for its remaining OBBBA funding, which expires on September 30, 2029. At its June-August pace, ICE would obligate only about half of its remaining OBBBA funding before it expires.
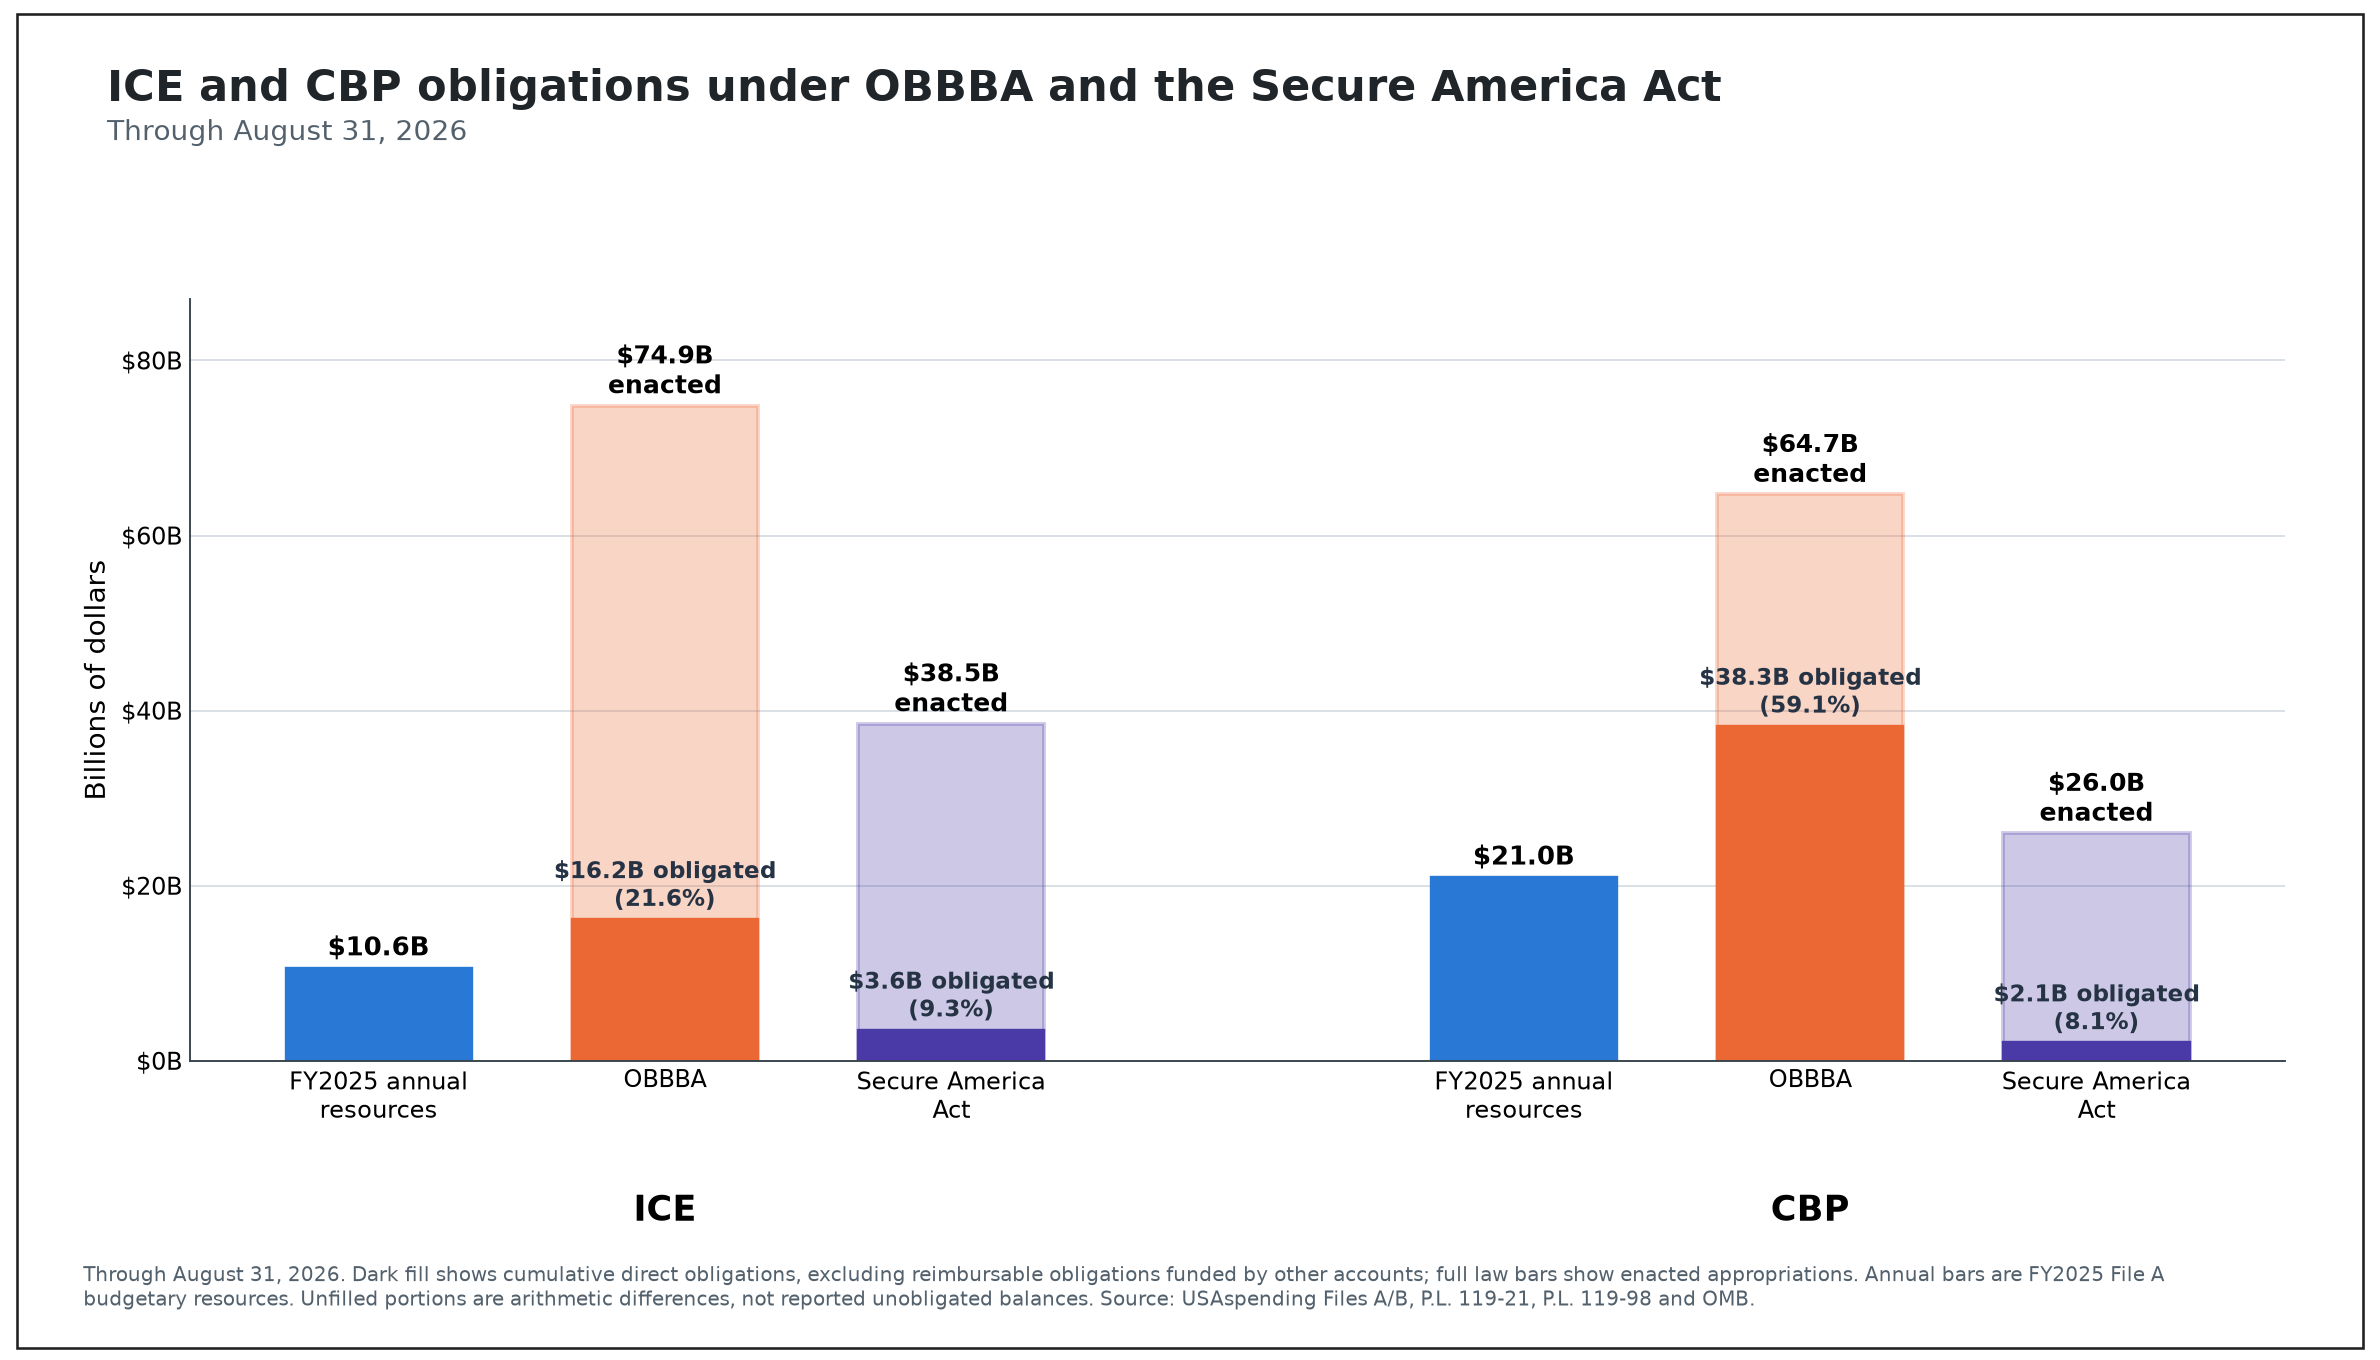
Figure 1. Dark bars show direct obligations through August 2026; the lighter bars behind them show the full amount each law provided. The gap between them is a simple subtraction, not the agencies’ reported balances discussed below. For scale, the FY2025 annual bars show the total funding available in each agency’s regular annual accounts in fiscal 2025.
These balances leave the annual appropriations in a situation without modern precedent. Congress uses annual appropriations to control agencies’ budgets, but ICE now has enough funding to continue operating for years without one. Yet the House Appropriations Committee has approved a new FY2027 DHS appropriations bill that would give the two agencies an additional $28.0 billion, and, more important, attach new conditions to their reconciliation funding. The sections below show what that money has bought so far: detention capacity at ICE and border infrastructure at CBP. The final section explains what the House bill would change, and why whether it becomes law in the lame-duck session will shape the oversight both agencies face in the next Congress.
ICE is spending reconciliation funds on detention and payroll
The graphic below matches the source of ICE’s obligations to their “object classes,” which are broad categories of what the obligations are being used for.
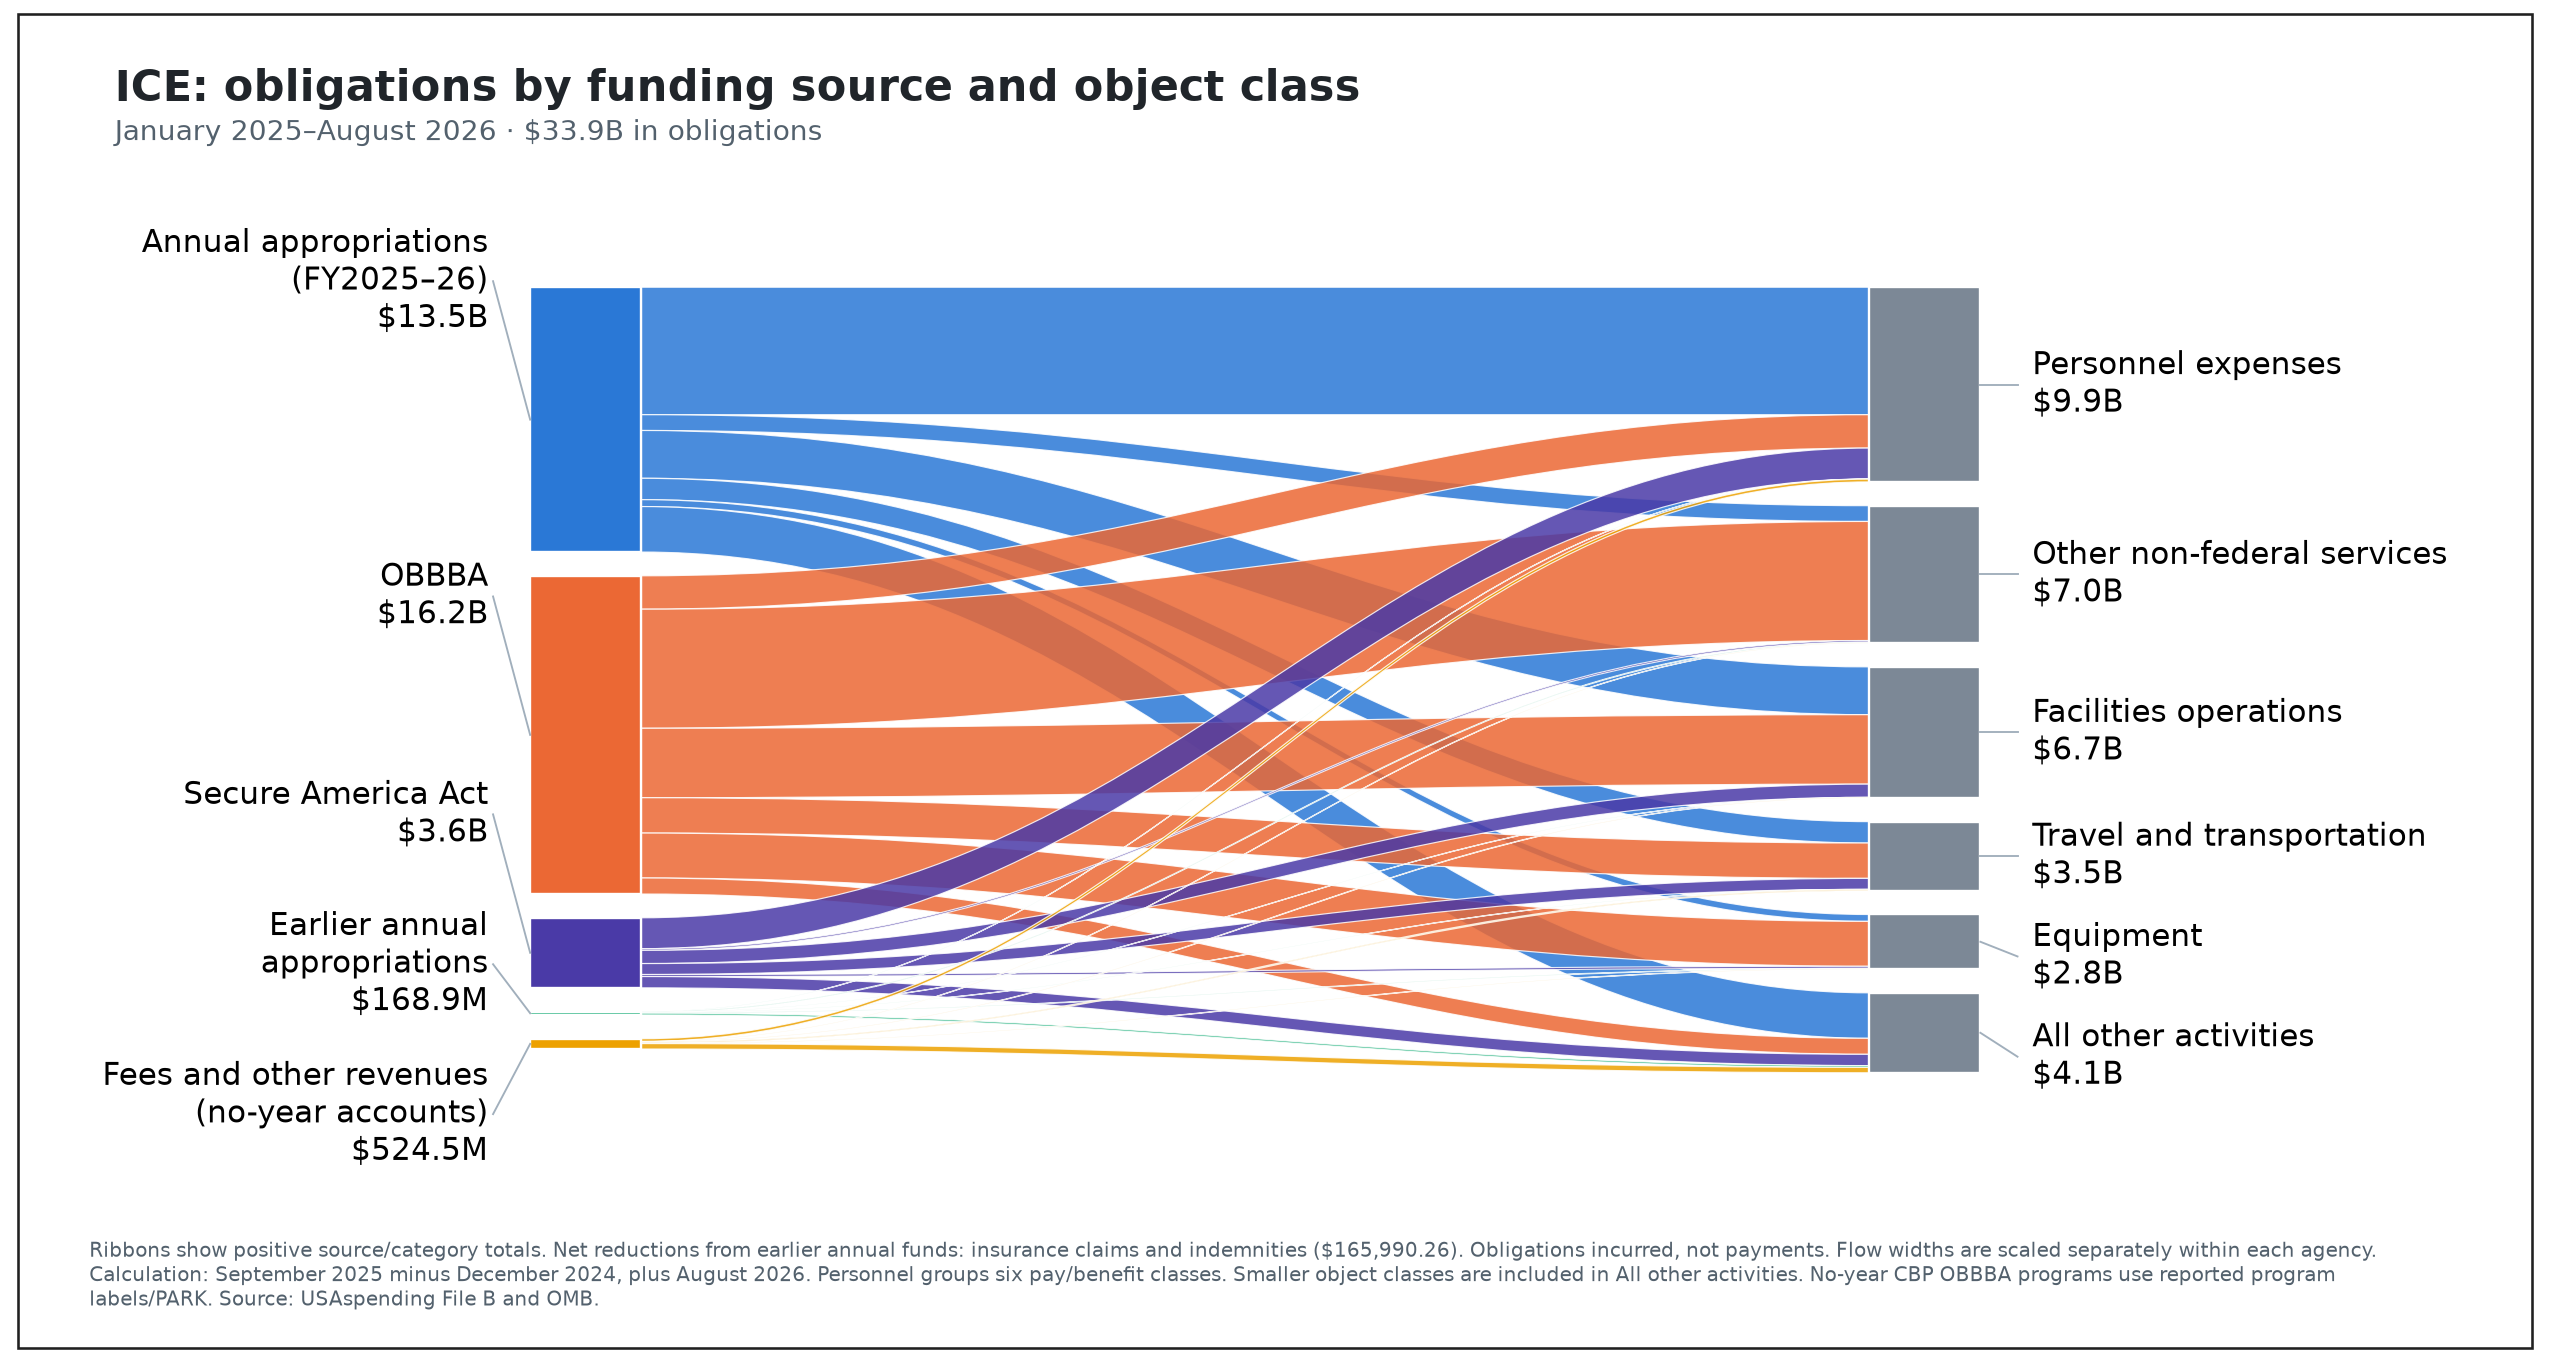
Figure 2. Funding sources are on the left; spending categories (“object classes” in budget terms) are on the right. Wider bands mean larger obligations. Sources include regular annual funding, the two laws, funding carried over from earlier years, and fees. The categories are accounting labels, not lists of facilities, contracts, or completed purchases.
From January 2025 through August 2026, ICE paid most of its personnel costs from its annual appropriations. But that funding is no longer available. ICE’s annual funding lapsed in February, and the April 30 law that funded the rest of DHS for the year extended ICE’s stopgap funding only through that date. Since May 1, ICE has had no annual appropriation, and it has turned to reconciliation funds to pay its workforce. It has charged $1.6 billion in personnel costs to the Secure America Act since that law was enacted in June.
ICE has used much of its OBBBA funding for detention. ICE reports obligating $6.1 billion of its OBBBA funding for “other services from non-Federal sources,” a broad catch-all category. $5.7 billion of that amount was recorded in ICE’s construction account, and ICE’s monthly budget reporting shows a nearly identical amount in the same account as “OBBBA - Detention Facilities.”
Most of ICE’s other OBBBA commitments went to facility operations ($3.5 billion), equipment ($2.3 billion), and travel and transportation of people ($1.8 billion). It has also directed $672 million of its SAA funding to facility operations and $559 million to travel and transportation. Last week, I showed how much of this spending could be flowing through state and local governments.
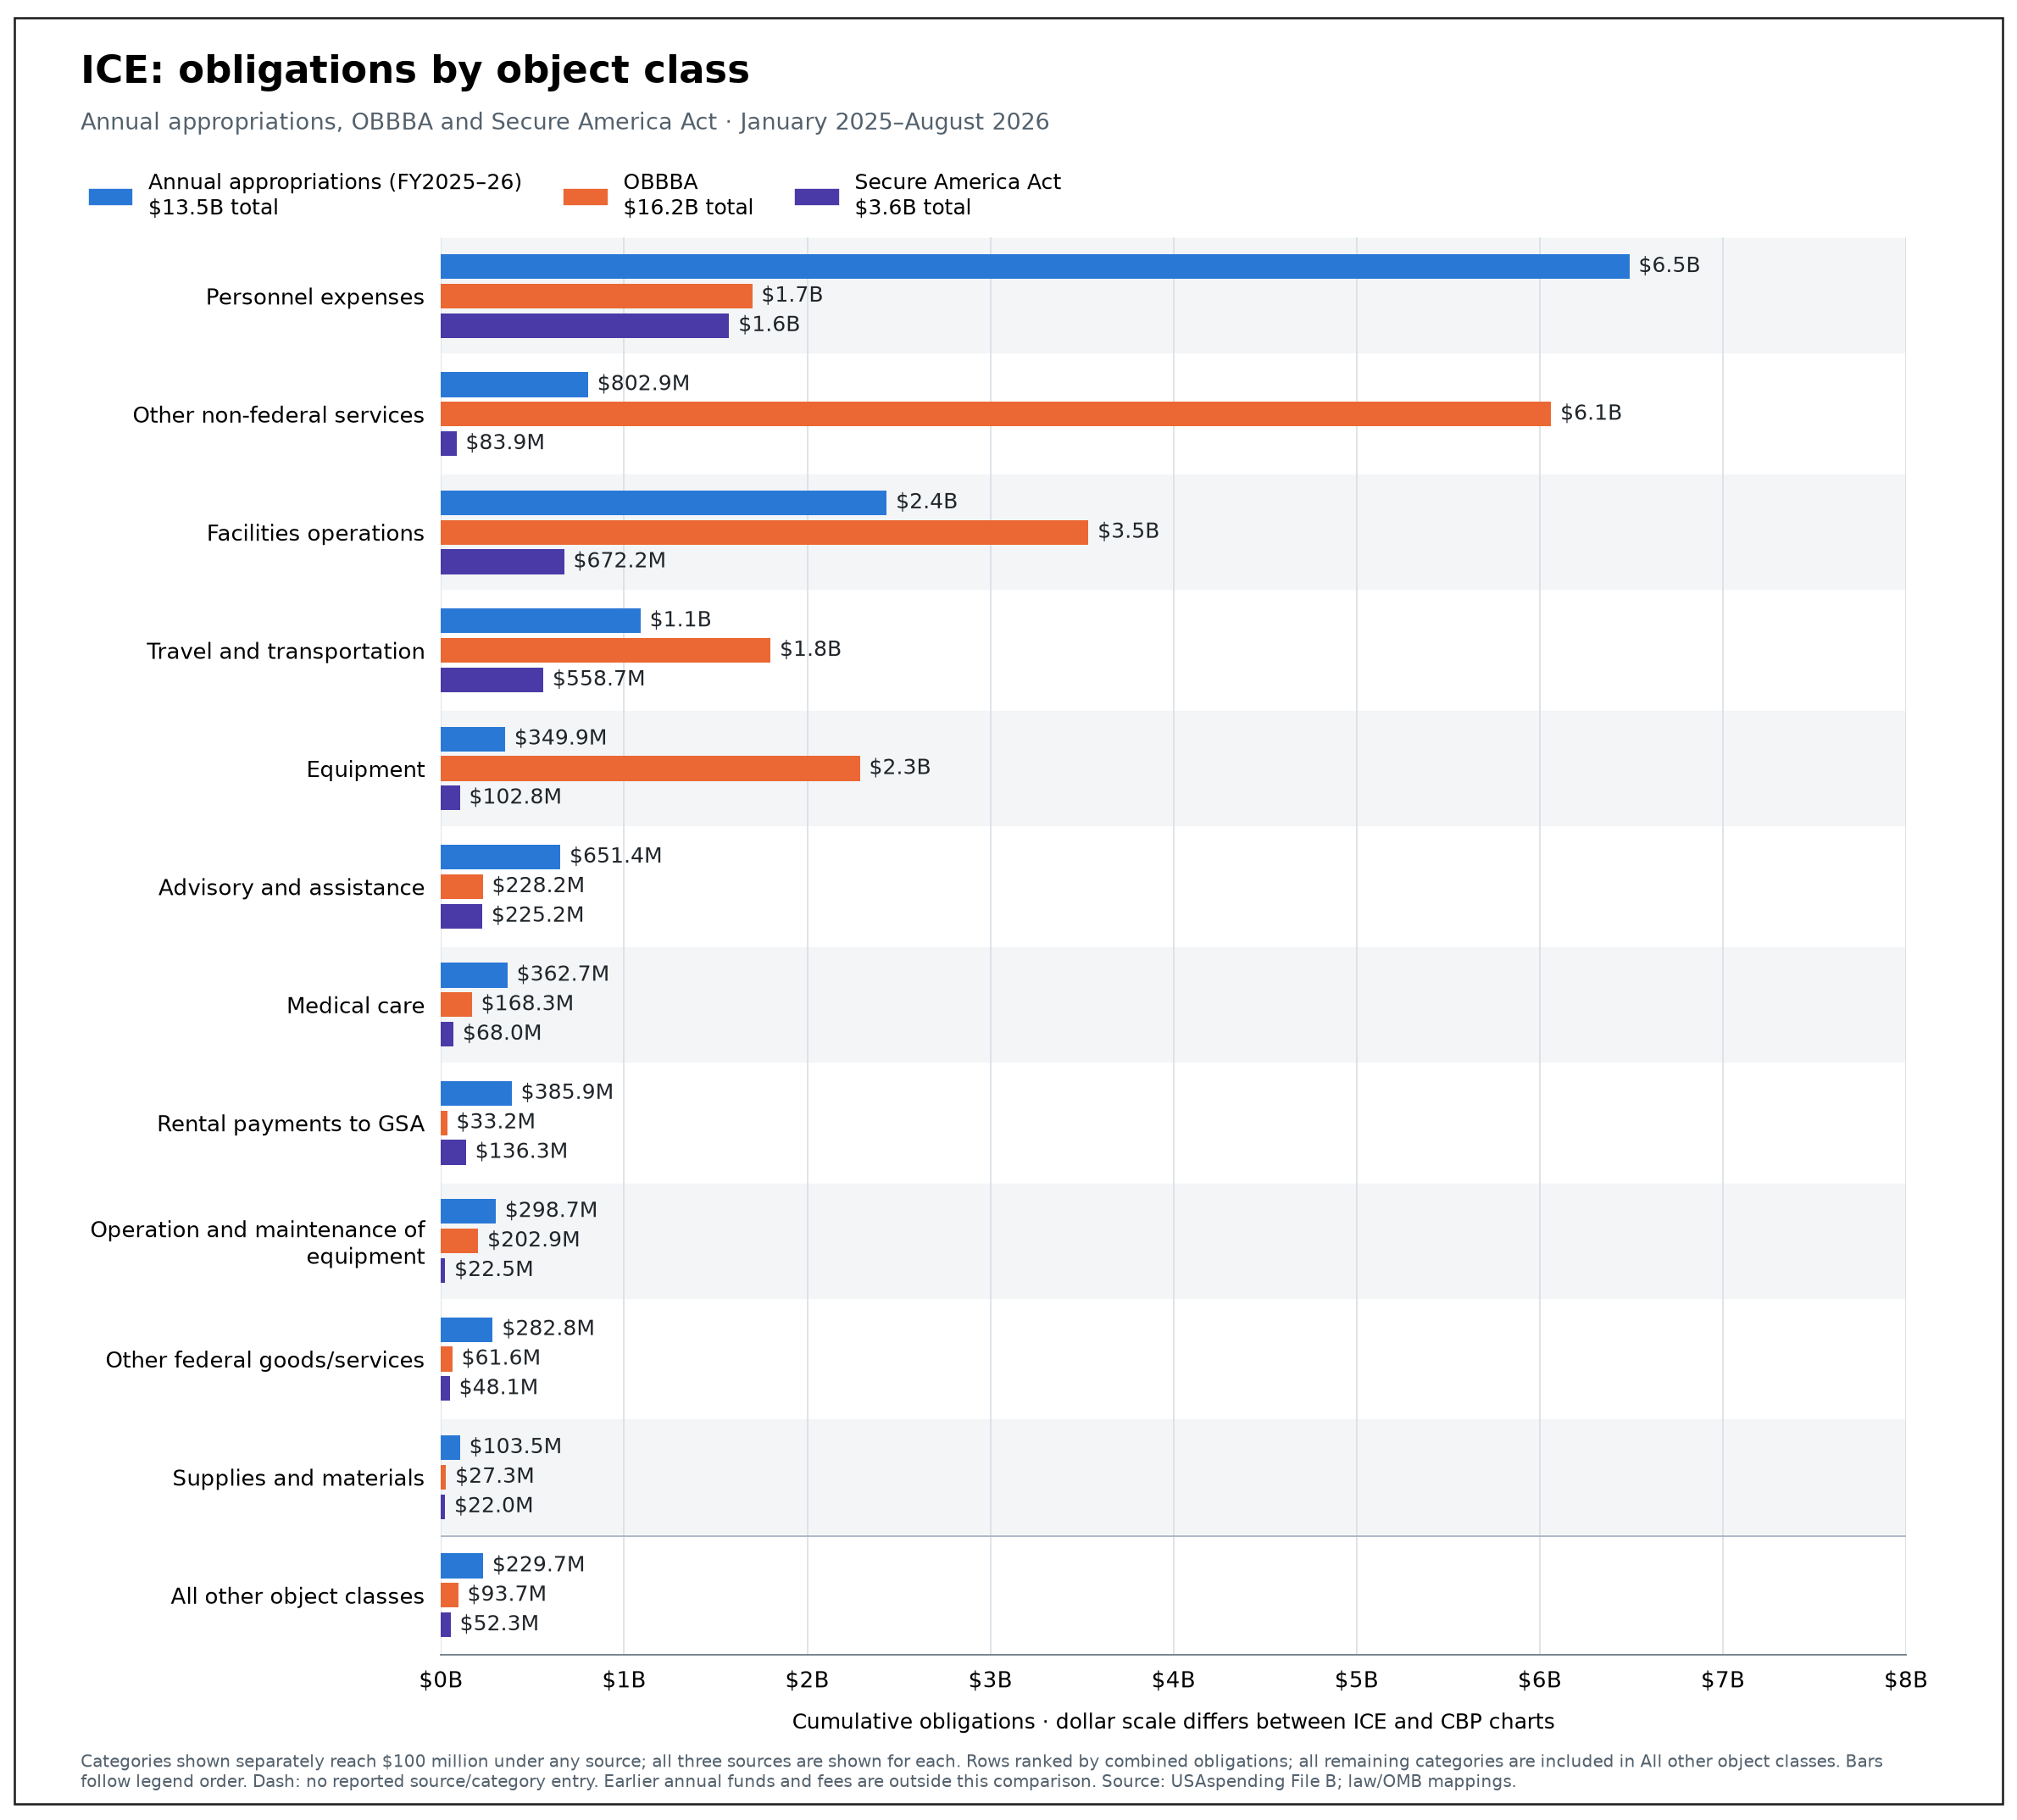
Figure 3. Blue is regular annual funding for fiscal 2025–26, orange is OBBBA, and purple is SAA. A category gets its own row if any source reaches $100 million; smaller categories are combined in the last row. A dash means no amount was reported, which is different from a reported zero. Funding carried over from earlier years and fees are excluded. Figures 3 and 5 use different scales, so compare bars within each chart.
CBP’s OBBBA funds are going to land and structures
CBP’s OBBBA commitments are far more concentrated. Of its $38.3 billion in OBBBA obligations, $32.0 billion (83%) is going to “land and structures” related to the border wall and other border security infrastructure. The majority of its obligations charged to its annual appropriation accounts, $22.0 billion (69%), are going to personnel costs.
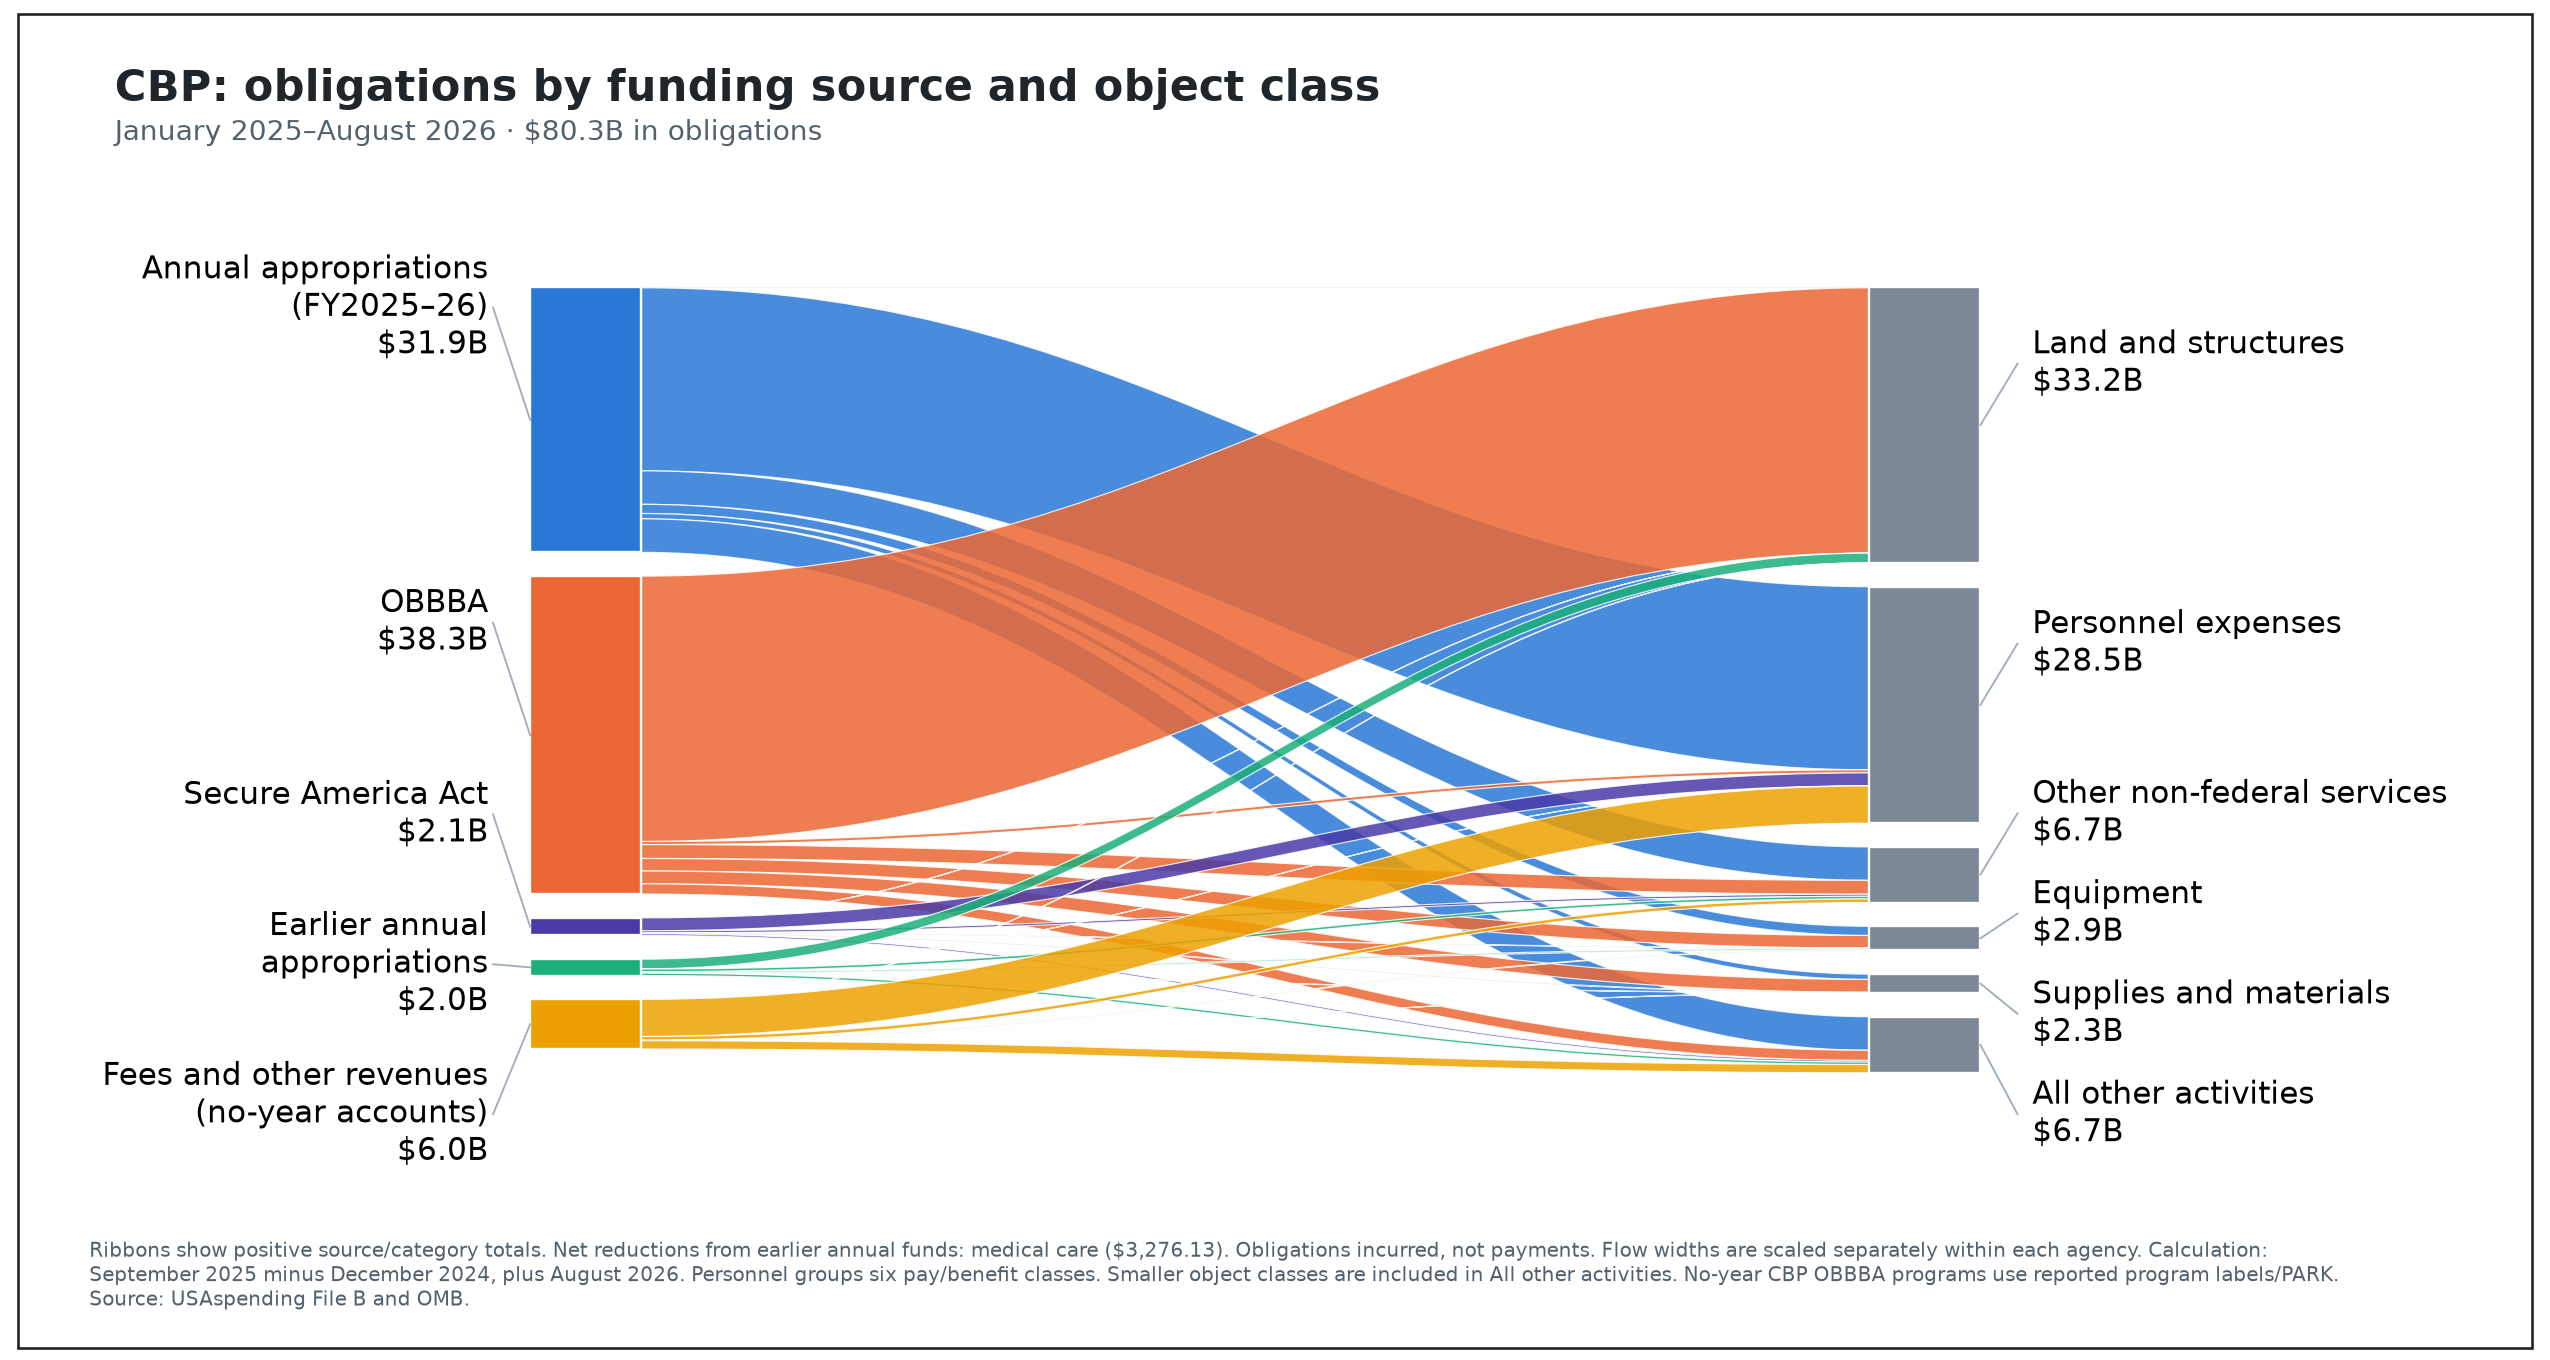
Figure 4. Same layout as Figure 2. Smaller categories are grouped as “All other activities.” The note lists small negative adjustments that cannot be drawn as bands.
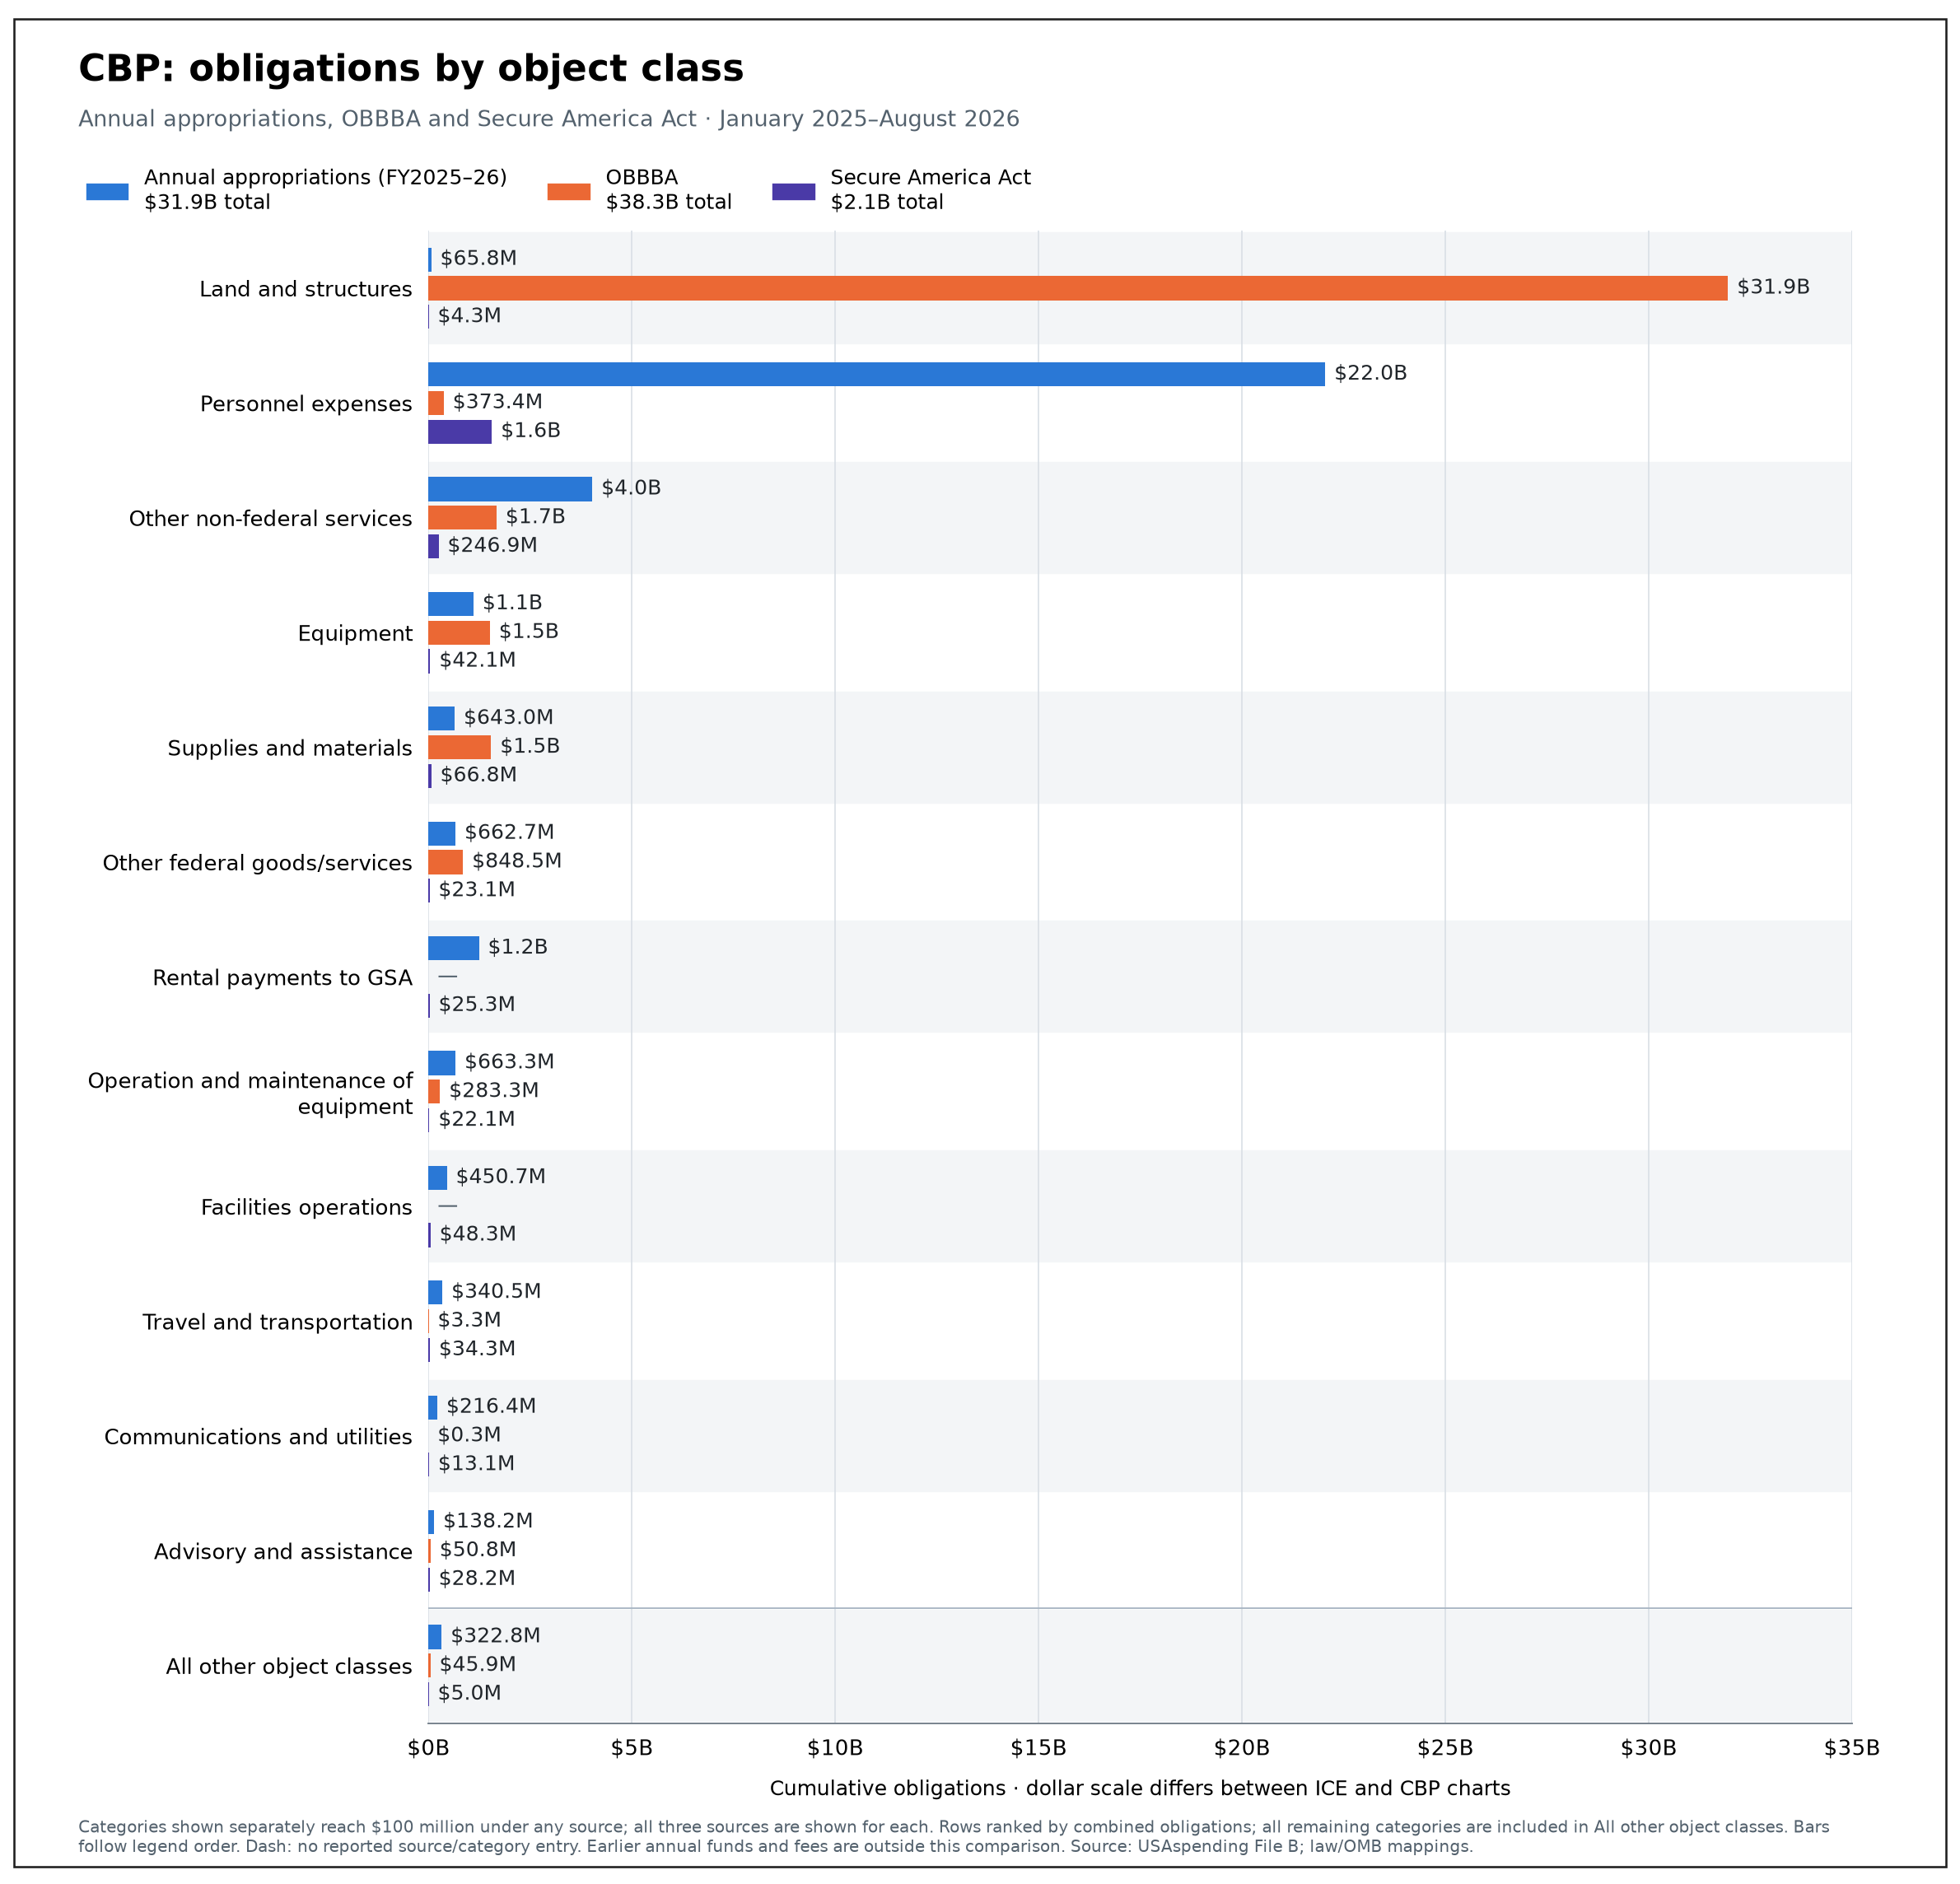
Figure 5. Same colors and selection rule as Figure 3, on a larger dollar scale.
What lies ahead
The DHS appropriations process is in what the Congressional Research Service calls “uncharted territory.” The FY2026 process produced the two longest partial shutdowns of any federal department since 1974, and ICE’s lapse lasted 116 days, until the Secure America Act ended it on June 10. ICE still has no annual appropriation, and it is operating on $93.6 billion in reconciliation funds, about nine times its previous annual funding. The House Appropriations Committee has now reported a FY2027 DHS bill with another $10 billion for ICE and $17.9 billion for CBP. The open question for the lame-duck session is how that bill would interact with the reconciliation money already provided.
Whether Congress passes a new annual appropriation for DHS could have important implications for oversight of ICE and CBP’s reconciliation funds. The Appropriations Committee’s FY2027 bill would not just include additional funding, but would attach new statutory conditions to ICE’s OBBBA and SAA funds, including:
- Extend protections for congressional visits to all funds. DHS would be barred from using any federal funds to keep members of Congress or their designated staff out of its detention facilities. Earlier annual DHS appropriations acts applied this protection only to their own funds. In January, after a court blocked an earlier version, DHS reissued a seven-day notice requirement for visits and said it would carry out the policy using only OBBBA money. When ICE’s annual funding lapsed in February, the government argued that the protection no longer applied. A federal court has ordered DHS to restore visits while a lawsuit by Rep. Neguse and other members proceeds; this provision would protect access however the case ends.
- Require a detention spending plan. Within 90 days of enactment, ICE would have to give the appropriations committees a plan for spending OBBBA’s detention funding. It would have to list the location, number of beds, and estimated cost per bed of every facility ICE used in the last quarter and its plans for the upcoming quarter. ICE would then report quarterly how actual spending compares with the plan.
- Require monthly reports on all of ICE’s money. ICE would have to submit an obligation plan covering every funding source, including reconciliation funds, fees, and balances carried over from earlier years, and update it monthly. Each update must show actual obligations, contracts extending past the fiscal year, and projections of when the funds for detention, alternatives to detention, and removals will run out.
Congress is in recess until after the midterm elections, and the current continuing resolution expires December 11. The lame-duck session will therefore determine whether this Congress enacts the FY2027 DHS bill and, with it, the new conditions on ICE’s reconciliation funds. If it does not, the decision passes to the next Congress, which will convene on January 3 and may have different majorities in one or both chambers.
Data and methods
The charts use USAspending Files A and B through August 2026, downloaded October 2, 2026. The funding-source and object-class totals cover January 2025–August 2026; the law-specific totals cover each law from enactment through August. Obligation totals and object-class breakdowns are calculated from File B. For the two reconciliation laws, the calculations include only direct obligations and use program information to identify OBBBA activity within CBP’s no-year construction account. Before excluding reimbursable obligations, File B totals are checked against File A’s account totals. File A also supplies the FY2025 annual-account funding amounts shown for comparison in Figure 1.
Each obligation was assigned to one of five funding sources based on the Treasury account that recorded it. Each account’s symbol states the fiscal years in which its funds may be newly obligated. The two reconciliation laws’ accounts were identified first and the remaining accounts were assigned by the year their availability begins:
- annual appropriations (FY25-FY26): accounts whose availability begins in FY2025 or FY2026, whether they are available for one year or several.
- OBBBA: ICE and CBP’s operations and construction accounts available from FY2025 and ending in FY2029, plus OBBBA facility programs that CBP reported in its no-year construction account.
- Secure America Act: ICE and CBP’s accounts available from FY2026 through FY2029.
- earlier annual appropriations: accounts whose availability began before FY2025 and still recorded obligations or adjustments during or after January 2025.
- fees and other revenues (no-year accounts): all remaining accounts with no fixed period of availability.
Figure 1’s enacted amounts are the funds that OBBBA and the Secure America Act appropriated directly to ICE and CBP: OBBBA sections 90001–90004 and 100052, and Secure America Act sections 101–103, 201, and 202. The obligations in Figure 1 and in the totals in the text are direct obligations, meaning those charged to these appropriations. They exclude reimbursable obligations, which the agencies paid for with money received from other accounts ($350 million at ICE and $11 million at CBP). The $144.0 billion remaining is the enacted amounts minus these direct obligations through August. The comparison to annual funding uses the total budgetary resources in each agency’s regular annual accounts in fiscal 2025, shown as the annual bars in Figure 1.
The agencies’ own monthly budget reports (SF-133, line 5324) show a larger remaining balance, $145.5 billion, for the seven ICE and CBP Treasury accounts that received the two laws’ funding. Nearly all of the $1.6 billion difference comes from money that moved within DHS. OBBBA also appropriated $10 billion for border support (section 90007) and $2.055 billion for immigration enforcement (section 100051) to the Secretary of Homeland Security, and the Secretary’s office directed about $1.8 billion of those funds to ICE’s and CBP’s OBBBA accounts. Of the approximately $1.8 billion traced to those provisions, ICE and CBP had obligated about $238 million through August. ICE and CBP also reported other reimbursable obligations whose originating statutory funding was not conclusively identified. The direct-only calculation excludes all reimbursable obligations, including those whose originating funding remains unresolved.
The run-rate estimates divide each law’s remaining funding at the end of August (the enacted amount minus direct obligations) by the agency’s average monthly direct obligations from that law in June, July, and August. Monthly direct obligations are the change in cumulative fiscal year 2026 direct obligations reported on the SF-133 (line 2004) between the end of May and the end of August, divided by three. CBP’s OBBBA figures include its no-year construction account. These estimates are illustrative and assume the summer pace continues; at that pace, ICE would not obligate its remaining OBBBA funds before they expire on September 30, 2029. Because the Secure America Act was enacted June 10, its average includes less than three full months of availability, and ICE recorded no SAA obligations until July.
The detention-facility connection uses two sources with different scopes. The $5.7 billion is File B obligations under “Other services from non-Federal sources” in the construction-and-facility-improvements program of ICE’s OBBBA construction account (Treasury account 070-2025/2029-0545), January 2025–August 2026. ICE’s August 2026 SF-133 reports $5.69 billion in fiscal year 2026 obligations for “OBBBA - Detention Facilities” in the same account.
Object classes are the government’s accounting categories for what obligations buy (see OMB Circular A-11 section 83 for full definitions). Personnel combines six pay and benefit classes. “Land and structures” and the other categories describe types of expenses, not individual projects, facilities, or completed purchases.
The legislative discussion draws on the enacted text of the fiscal 2026 Homeland Security appropriations act (P.L. 119-86) and the current continuing resolution (P.L. 119-103), and on the committee-reported text of the House fiscal 2027 bill (H.R. 9310).
The analysis does not assign the Secure America Act funds appropriated to the Office of the Secretary to ICE or CBP. All figures use the versions of the reports saved with the accompanying data; later revisions may change them.
I used two AI tools, Anthropic’s Claude and OpenAI’s Codex, to help build the data pipeline, check calculations against the source records, research legislative and legal sources, and edit the text. I reviewed their work, and I am responsible for the analysis and any errors.